


January 14, 2026
Brand matters
Big movers and clear leaders emerge in our 2025 Global Top 50 P&C Reinsurance Brand Rankings.
Competition in SFS is intensifying and broadening, although markets and solution segments are evolving at different speeds as regulatory treatment, insurer familiarity and transaction experience evolve on different trajectories.
Demand for SFS transactions is increasing globally, with competition expanding across regions that differ in their levels of segment maturity and in their regulatory and accounting regimes.
It may be a cliché to say so, but the SFS reinsurance market is genuinely dynamic. While the cadence is not quite a steady drumbeat, new transactions are announced by reinsurers each month across a diverse range of markets. These announcements represent only a part of the underlying deal activity.
Given the lead time to deal completion, it is reasonable to expect this momentum to continue, and most likely accelerate, as reinsurers increase their focus.
Solution types also differ between and within markets, shaped by evolving solvency and regulatory capital regimes, creating opportunities for solution innovation to meet differing insurer requirements.
Among the key SFS markets globally, the US is the largest and most established, while the UK has a long history with longevity solutions and funded reinsurance (PRT). Activity in Asia is significantly on the rise, especially Japan and Hong Kong for asset-intensive solutions.
Developments in Continental Europe are more fragmented. Mass-lapse reinsurance is well established in several countries, while in others (including Spain) regulatory acceptance for this relatively ‘vanilla structure’ remains a hurdle. A few high-profile asset-intensive deals have been completed in Europe, which may well pave the way for a ramp-up in activity, once regulatory responses are fully understood.
Competitors differ in their areas of focus and risk preferences, from financing and reserve-relief structures to full risk transfer and asset-intensive structures at the other end of the spectrum. Depending on the transaction, this may bring reinsurers and specialist providers into both competition and partnership at times, as well as create significant opportunities for advisers.
Having established that demand and appetite vary by market, it is important to note that there is also an evolutionary dimension: markets and solution segments will not necessarily follow the same path.
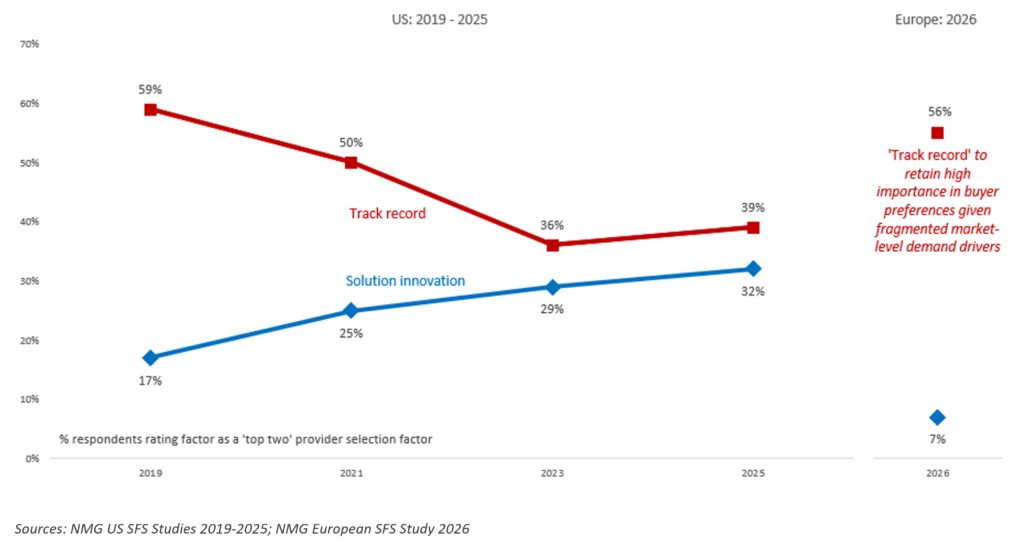
A comparison of provider-selection preferences among senior insurance executives suggests that the early establishment of a track record (with the offer of ‘completion certainty’) can provide competitive differentiation and thus a first-mover advantage in the form of reputation.
In 2026, a credible track record is the leading selection factor for buyers in Europe, ranked among the top two preferences by 56% of executives, comparable to the 59% recorded in the US in 2019.
In contrast, currently solution innovation is ranked among the top two provider-selection factors by just 7% of European executives. The most relevant comparable could be the preferences of US buyers from 2019 and before, meaning that solution innovation may grow in importance in the years to come.
Exhibit 1: Track record matters in SFS partner selection
Early establishment of a credible track record delivers advantage and competitive momentum. Solution innovation grows in relevance once structures gain acceptance and become mainstream
Reflection: The efforts required to deliver the first transaction in a market could indeed set the highest bar for innovation success, given the high degrees of uncertainty and patience involved and usually non-linear nature of the process.
For global reinsurers, the question is thus not only where to compete, but how to adapt the proposition to markets, current and future. What wins in one market cannot necessarily easily be replicated in another. And what wins today may not be what sets providers apart tomorrow.
Reinsurers therefore need to adapt their propositions and partnerships at market level, as a one-size-fits-all approach is unlikely to be optimal.
Looking ahead, this points to a competitive landscape with regional/country champions and perhaps a few genuinely global franchises capable of adapting to different environments.
If you would like to find out more about NMG’s global SFS Studies, please get in touch with us.